Categories
How to Enroll in Medicare and Medigap
by Wylie Wang | November 6, 2026 | Articles, Health Insurance, Retirement
Eligibility
Your Medicare coverage will start on the first day1 of the month you turn 652. For example, if your birthday is December 15th, 1961, your Medicare will start on December 1st, 2026. Your initial eligibility window will be 7 months: 3 months before your birthday, your birthday month, and 3 months after your birthday. For the December 15th, 1961 birthday, your eligibility window is from September 1, 2026 to March 31st, 2027.
What to Enroll In
If you are retired or will be retired at 65, you will enroll in both Parts A & B. These parts combined cover 80% of all covered medical costs. Part A is free3, while Part B has a monthly premium of $202.90 as of 2026.
If you are still working and receive eligible4 health insurance through work, you may delay Part B enrollment without any penalty until you lose your health insurance. Otherwise, you must enroll in Part B or face a 10% permanent increase in your Part B monthly premium for every year you delay.
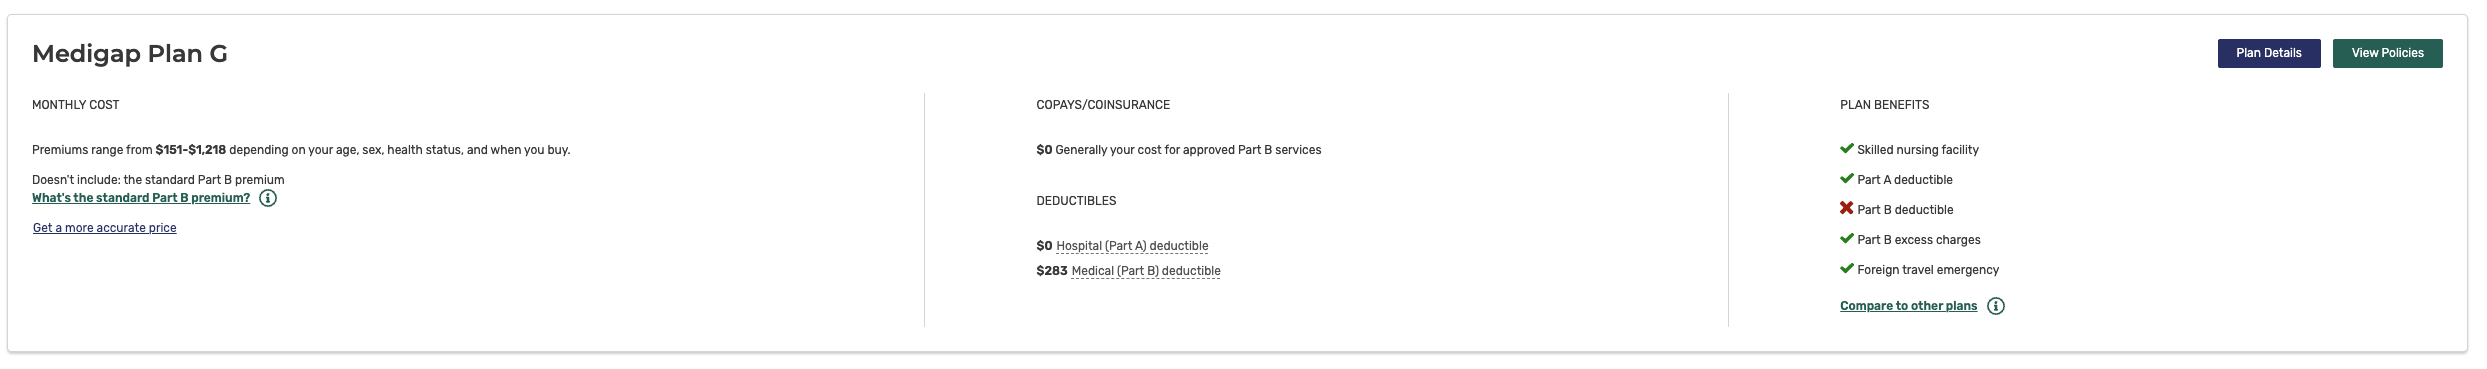
To cover the remaining 20% of medical costs, you can enroll in either a Medicare Supplemental Plan (known as Medigap) or Part C (known as Medicare Advantage). Most often, Medigap Plan G makes the most sense, as it is the most comprehensive supplemental plan available to new enrollees, covering nearly all costs beyond the annual Part B deductible of $283, as well as some foreign travel emergency care.5
Medigap vs. Medicare Advantage Plans
Medicare Advantage plans (Part C) are similar to your normal private health insurance plan, such as ones offered through work. They will have similar restrictions on in-network and out-of-network providers. Meanwhile, Medigap allows you to see any provider who accepts Medicare, with no in-network or out-of-network distinction. Most importantly, during your initial enrollment, you get a one-time eligibility window to sign up for Medigap without medical underwriting. This is extremely important, as you cannot be denied or charged more for any poor health or pre-existing conditions. For these reasons, we generally recommend Medigap over Medicare Advantage.
In Connecticut, Maine, Massachusetts, and New York, however, you retain the right to sign up for a Medigap plan annually, without medical underwriting even after the initial enrollment period. Thus, in these states, it is safer to shop around between a Medigap plan and a Medicare Advantage plan, as you can always switch back to a Medigap plan during open enrollment.
Part D
Medicare Part D is an optional benefit that covers prescription drugs. As in Part B, if you do not enroll during your initial eligibility period, you will incur a penalty: a 1% monthly premium increase for each month you delay enrollment. However, if you have creditable coverage provided by work, you may delay Part D without penalty. There is a monthly premium associated with Part D, and it varies by plan. Regardless of the prescriptions used during enrollment, we think it’s wise to enroll in Part D, as one’s health often changes throughout retirement.
Where to Enroll
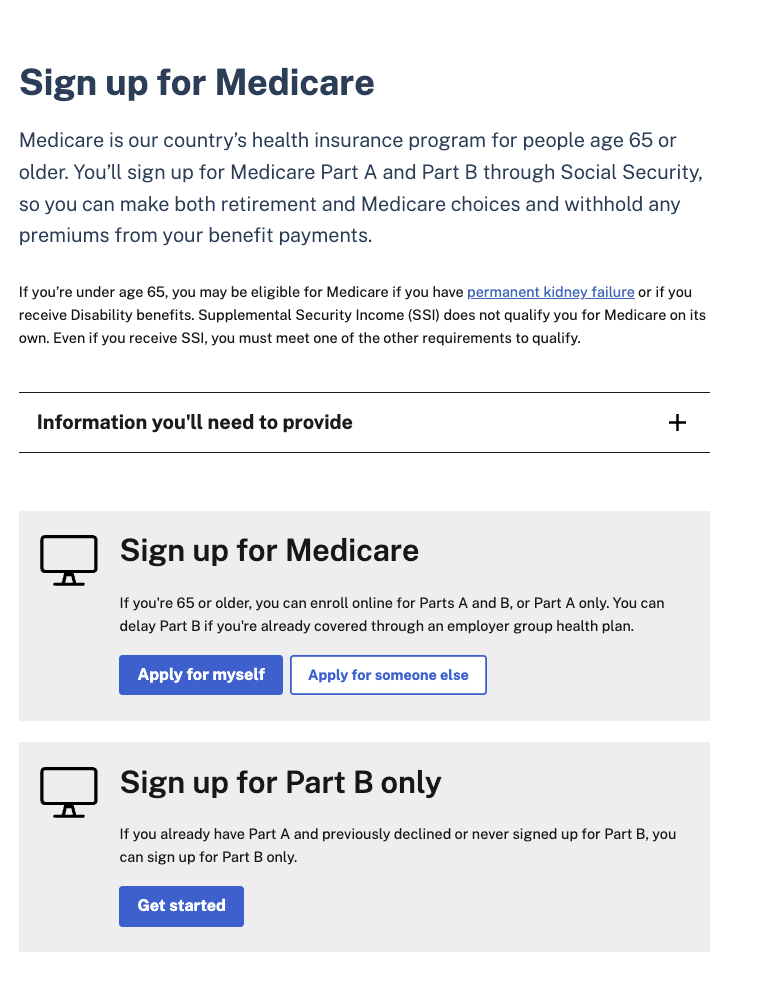
Parts A and B Enrollment
Sign up at https://www.ssa.gov/medicare/sign-up
Medigap Plan G Enrollment
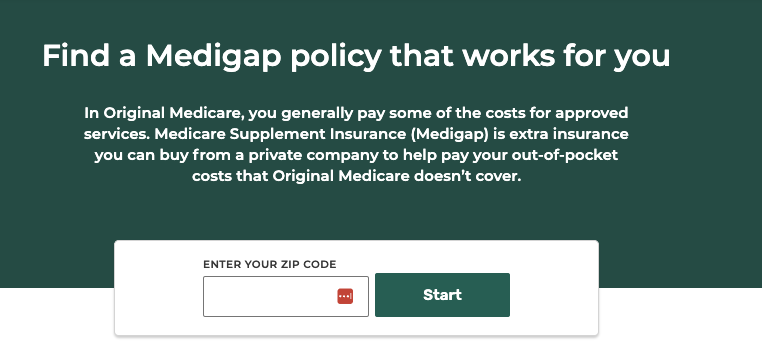
Go to https://www.medicare.gov/medigap-supplemental-insurance-plans/
Enter your zip code and click Start.
Scroll down until you see Medigap Plan G, and click View Policies.
Enter your zip code, age, sex, and tobacco status, and click Update Prices. Choose a company and call them to enroll in their plan.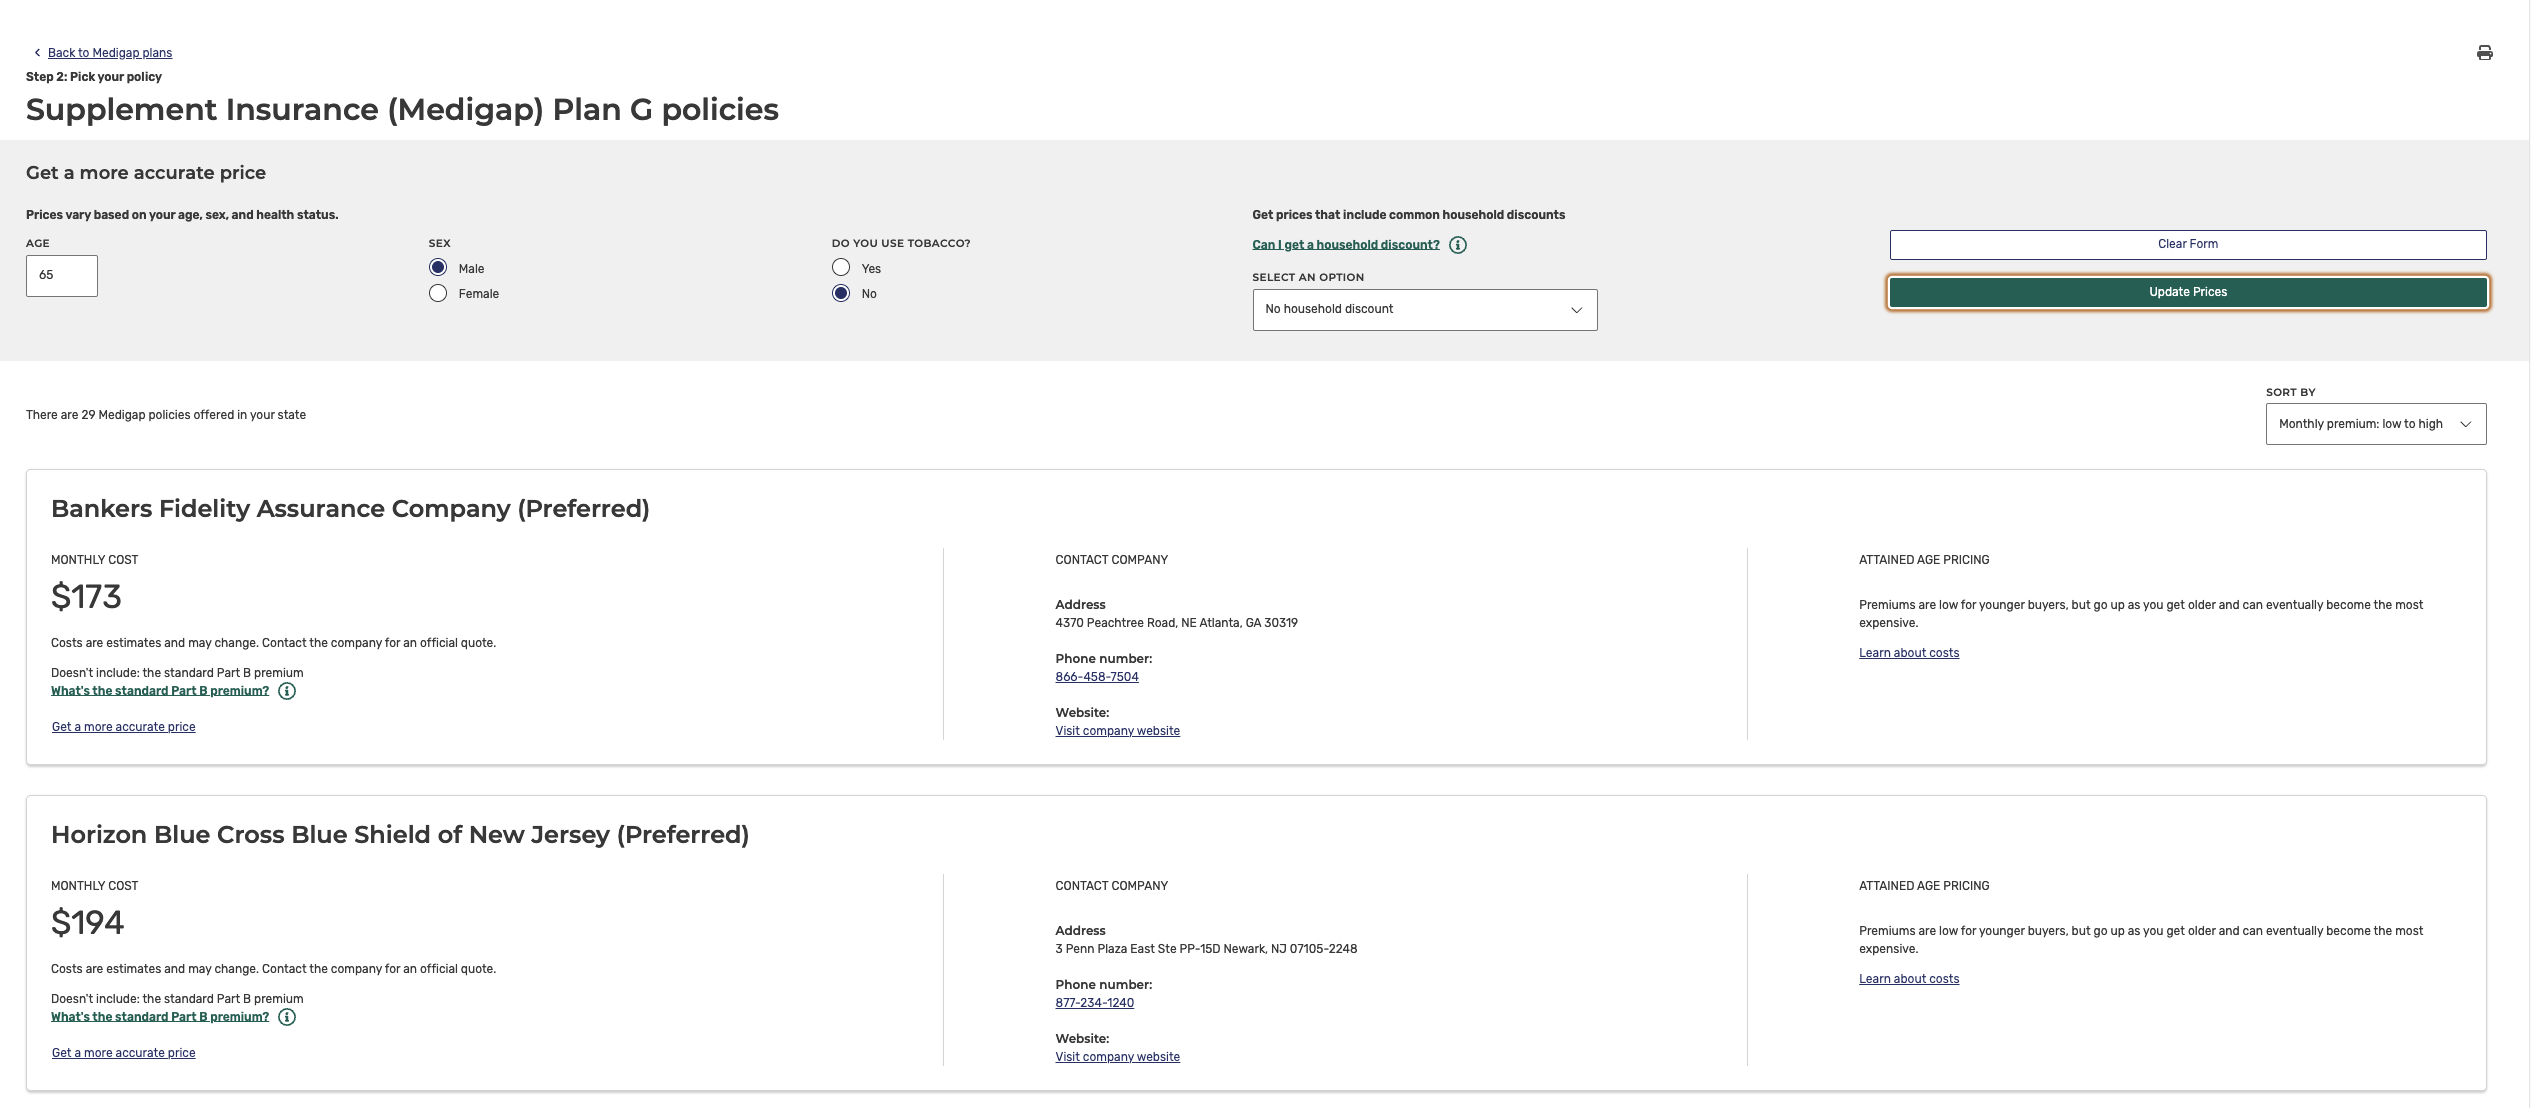
Note: There are three ways the Medigap policy can be priced.
- Community: Everyone pays the same Price
- Attained: As you grow older, you will pay more
- Issue: Price is fixed to when you first enrolled in the plan
All three pricing methods may also increase due to inflation and changes in medical costs.
Part D Enrollment
Go to https://www.medicare.gov/plan-compare
Select your coverage year and type in your zip code.
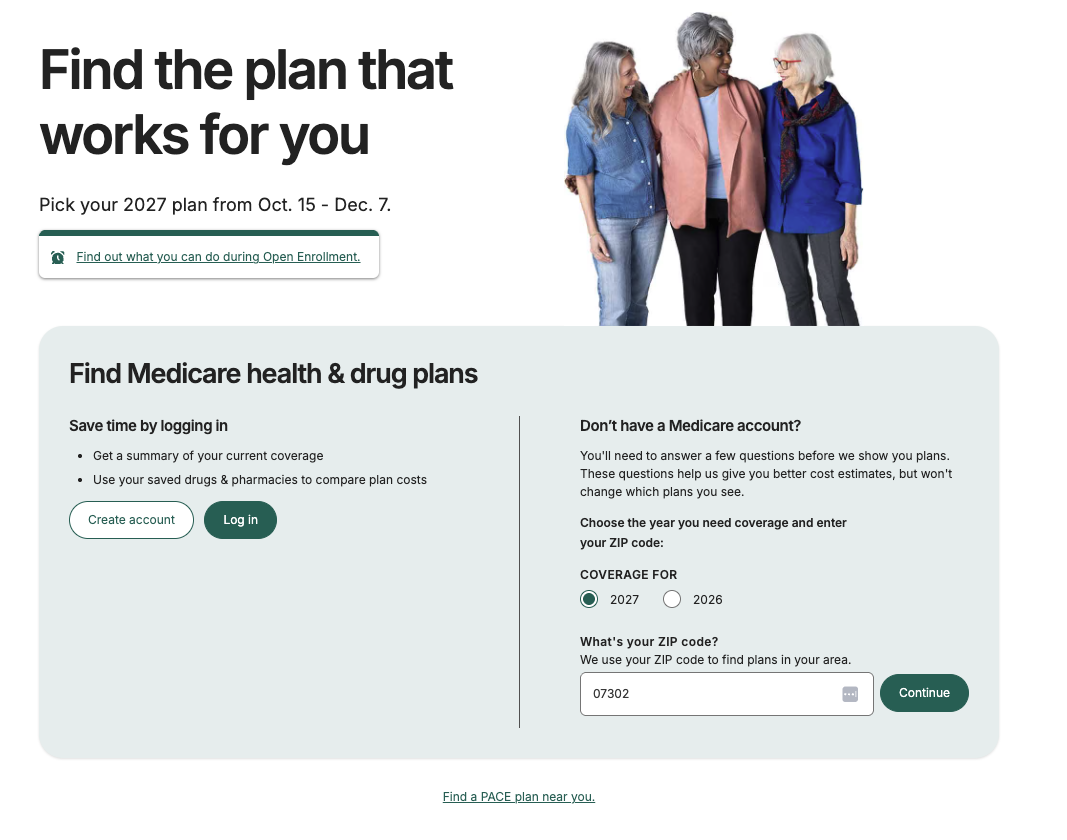
Select Medicare drug plan (Part D) and click Find Plans
Answer the next few questions and enter all of your prescription drugs.
Choose the plan that minimizes monthly premium and drug copayments. The plans will automatically be sorted, with the first plan being the cheapest overall after factoring in monthly premiums and drug prices.
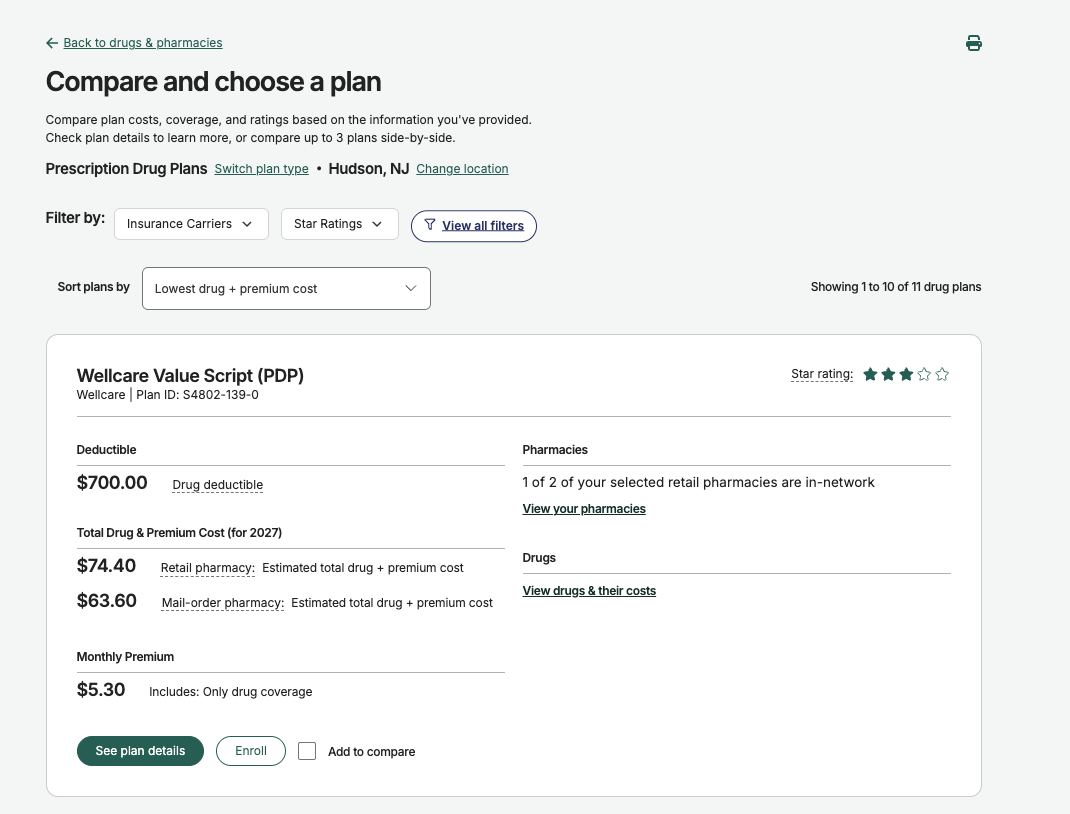
You can switch plans every year, so if your drug costs increase, you should be sure to shop around during open enrollment.
How to Get Help
If you need help, you can contact your state's SHIP agent. You can find them here: https://www.shiphelp.org. SHIP is a state-run, federally funded program that provides free help in choosing a Medicare plan.
1 If your birthday is on the 1st of the month, you will actually be eligible the month BEFORE your birthday.
2 If you have a disability, end-stage renal disease, or ALS, you may be eligible for Medicare before 65.
3 As long as you have 10 years of work credits with the SSA.
4 To be eligible, your employer must have 20 or more employees.
5 https://www.medicare.gov/health-drug-plans/medigap/basics/compare-plan-benefits Medicare publishes a chart of all Medigap plans and their coverages. Plan G is the most comprehensive plan available to new retirees.